Renovation and construction loans help you purchase, build, or remodel a home while also covering renovation costs in one financing plan. These programs may bundle the home and improvement costs into a single loan, making it easier to budget, upgrade, and create a home that fits your needs and lifestyle.
Renovation and construction loans are designed to finance the cost of home improvements, remodeling, or new home construction. These loans allow homeowners and buyers to upgrade, repair, or build properties with structured financing that releases funds in stages as work is completed.
These loans are ideal for homebuyers purchasing fixer-uppers, homeowners looking to renovate, and individuals building a custom home. Investors can also use these loans to rehab properties for resale or rental income.
Unlike traditional mortgages, renovation and construction loans provide funding in stages rather than a lump sum. Lenders disburse payments based on project milestones, ensuring that contractors and builders receive payments as work progresses.
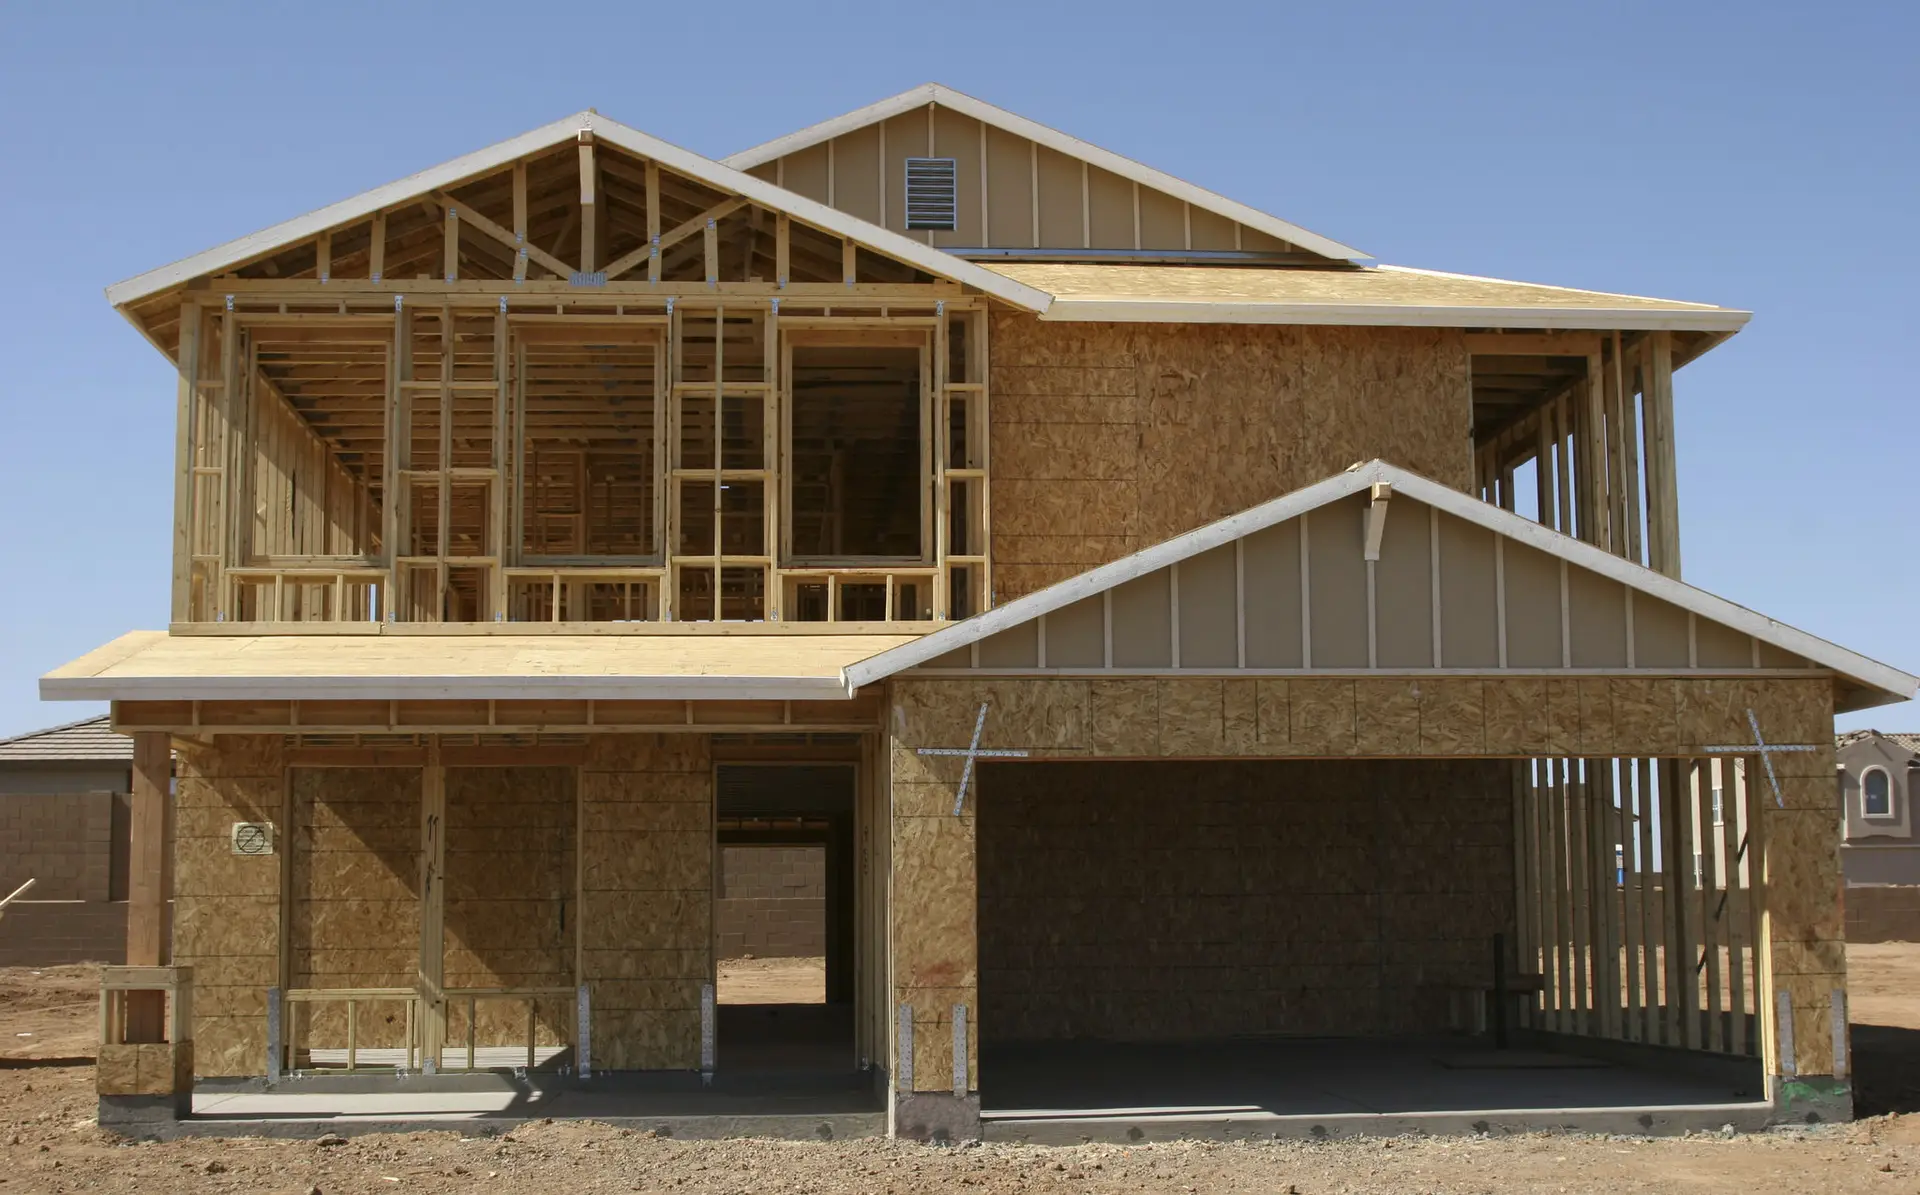
Loan options include FHA 203(k) renovation loans, Fannie Mae HomeStyle loans, VA renovation loans, construction-to-permanent loans, and standalone construction loans. Each loan type has different requirements based on the scope of work, borrower qualifications, and loan terms.
These loans provide flexible financing for remodeling, home improvements, or new construction. Borrowers can increase their home’s value, customize their living space, and spread renovation costs over time instead of paying upfront.
If you’re looking to upgrade your home, purchase a fixer-upper, or finance a custom-built home, a renovation or construction loan may be the perfect solution. A mortgage specialist can help determine the best loan option for your project.
Jon Shrum, President of KMC Financial and Team Shrum, helps buyers and homeowners finance both the home and the improvements with one clear plan. He guides you through contractor bids, timelines, and loan options, and keeps the process organized from start to finish. With honest advice and close attention to detail, Jon makes building or renovating feel manageable.
A construction or renovation loan works best when the scope, documentation and payment schedule are understood by everyone involved.
Clarify whether the project is a renovation, a purchase needing work or a new build, along with the proposed scope and occupancy timeline. Different structures have different approvals. Share those details with Team Shrum before treating a general mortgage preapproval as project financing.
The lender may require plans, permits, itemized bids, contractor credentials and a completion schedule. The acceptable contractor and work depend on the program. Gather the required documents before promising a closing or start date that assumes they are already approved.
Under many programs, the lender releases funds through draws after required verification or inspections. The contract and loan must have compatible payment expectations. Clarify who requests draws and how changes are approved before committing to deposits or progress payments.
Budget a suitable contingency and any temporary housing or overlapping payment costs. Ask what the agreement allows if the project runs over budget or time. Additional financing and extensions require approval; they are not a substitute for a realistic plan.
The arrangement may have one combined closing or a separate permanent loan, with different rate and approval conditions. Ask which inspections, valuation or documents remain at completion and when regular payments begin. Early construction approval does not settle every later requirement.
If eligible, a HELOC, fixed home equity loan or cash-out refinance may be alternatives. Compare the effect on the existing mortgage, payment changes and total cost. Match the borrowing schedule to the work while keeping the combined household obligation manageable.
Information checked September 6, 2026. Sources: CFPB: Construction loans · HUD: FHA 203(k) program · Fannie Mae: HomeStyle Renovation · CFPB: Construction loan disclosures.