Conventional Home Loans

Conventional home loans offer competitive interest rates, flexible terms, and low down payment options for qualified buyers and homeowners. They are a popular choice for purchasing or refinancing primary homes, second homes, and even investment properties, giving you predictable payments and long term stability.

Conventional Home Loans

What Are Conventional Home Loans?

Conventional home loans are mortgages that are not insured or backed by the government, making them one of the most flexible and widely used financing options. With low down payment requirements, competitive interest rates, and fewer restrictions, they are ideal for buyers with strong credit.

Who Can Benefit from a Conventional Loan?

Conventional loans are great for first-time and repeat buyers, those with good credit and stable income, and anyone looking for customizable loan terms. They also work well for homeowners refinancing for better rates or tapping into home equity.

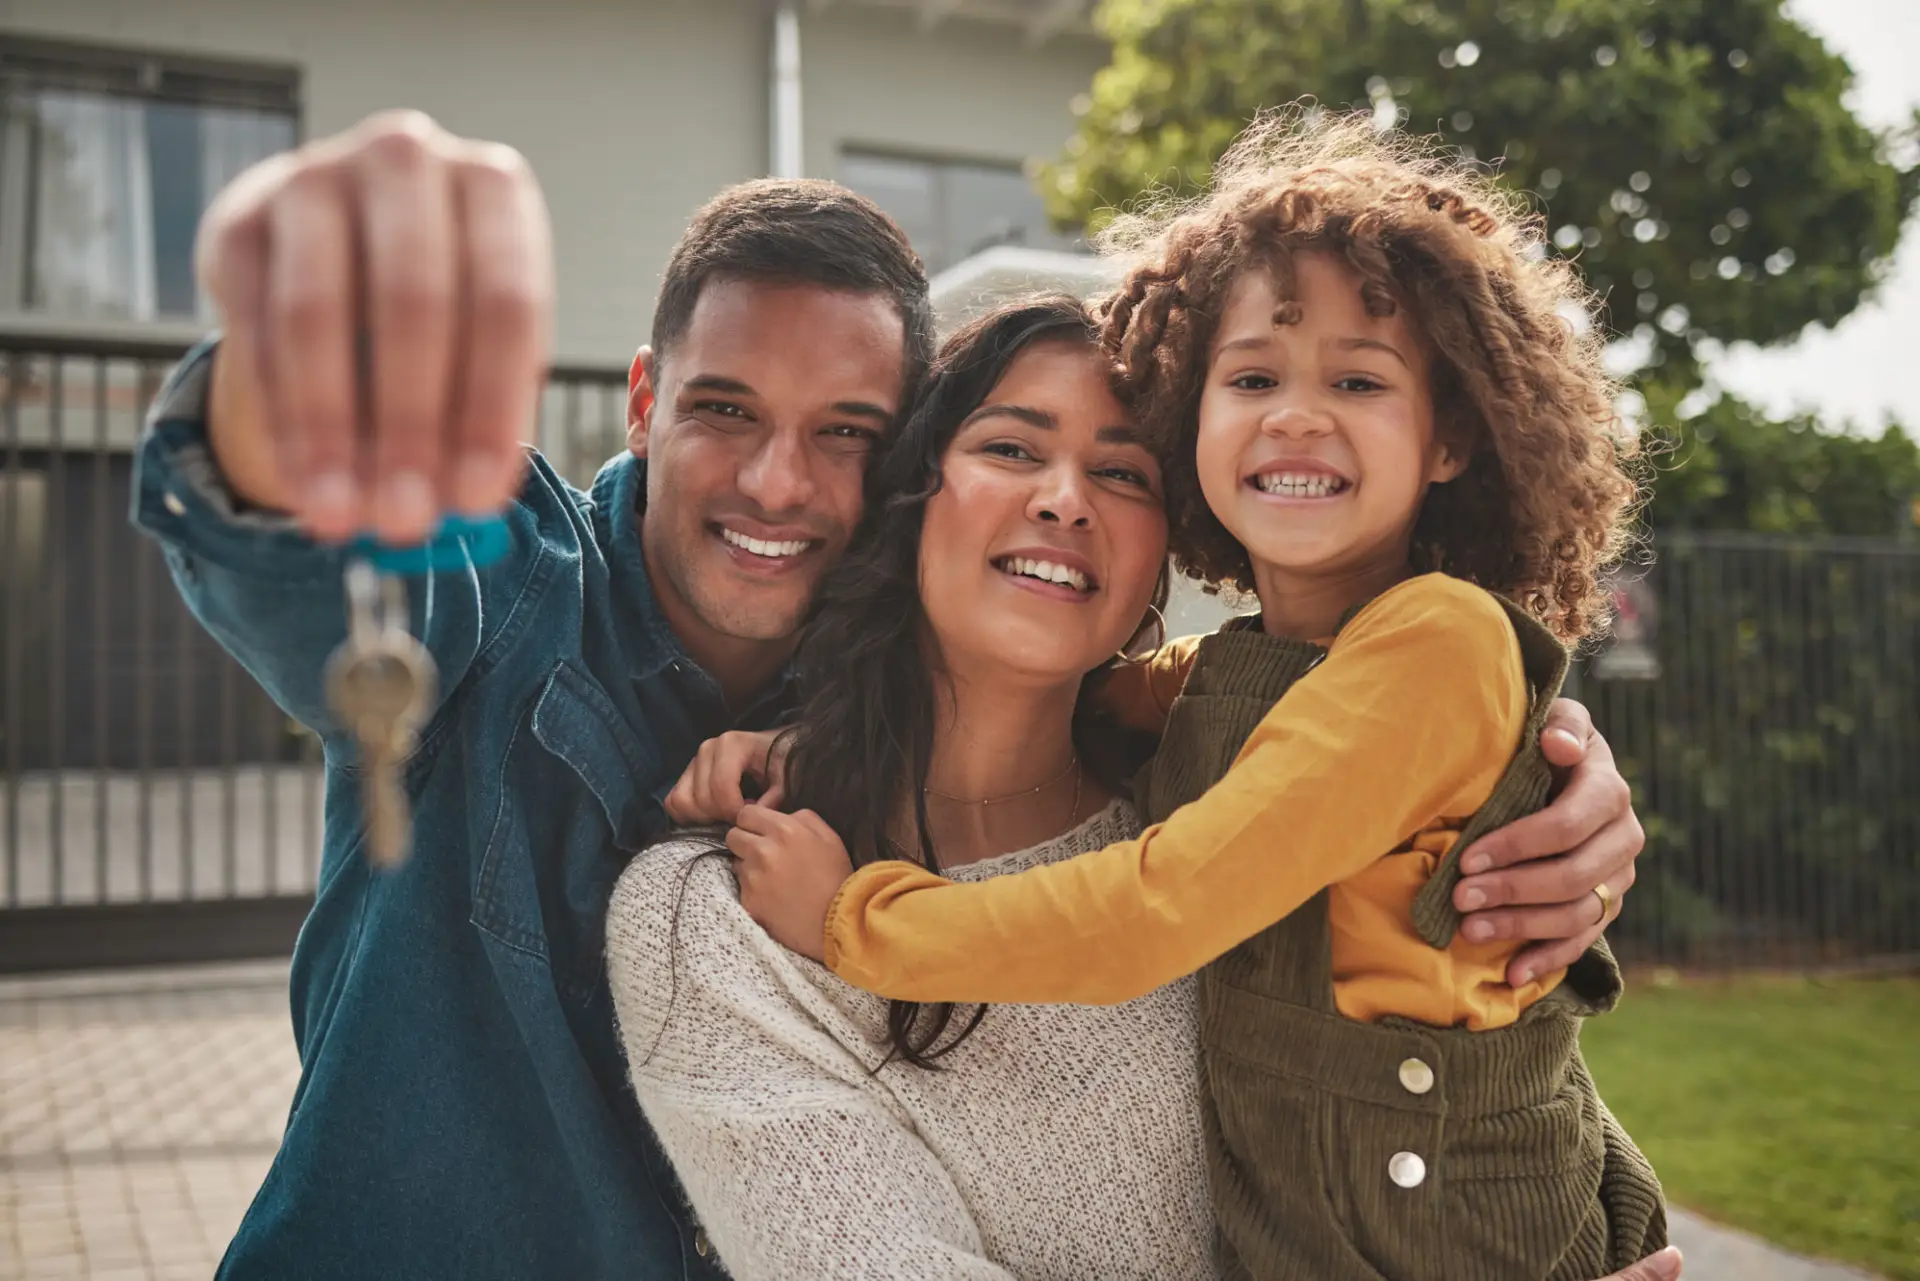
Family holding up the keys to their first home outside the front door

How Do Conventional Home Loans Work?

A lender evaluates your credit score, income, and debt-to-income ratio to determine your eligibility. These loans can be fixed-rate or adjustable-rate and offer term lengths from ten to thirty years, giving you flexibility in repayment.

Types of Conventional Loans

Conforming loans meet Fannie Mae and Freddie Mac guidelines and offer competitive rates. Non-conforming loans, such as jumbo loans, are designed for higher-priced homes that exceed standard loan limits. Fixed-rate loans provide stable payments with a locked-in interest rate, while adjustable-rate mortgages (ARMs) start with a lower initial rate and adjust over time.

What Are the Benefits of a Conventional Loan?

Conventional loans allow down payments as low as three percent for qualified buyers. With a twenty percent down payment, private mortgage insurance is not required, reducing long-term costs. These loans offer competitive interest rates, flexible term options, and can be used for primary homes, second homes, and investment properties.

Is a Conventional Loan Right for You?

If you have good credit, stable income, and want lower long-term costs, a conventional loan could be your best option. Whether you’re buying a new home or refinancing, it offers more lender flexibility and fewer fees than government-backed loans.

Why Use Jon Shrum for Your Conventional Loan

Jon Shrum, President of KMC Financial and Team Shrum, helps buyers and homeowners secure conventional financing with competitive rates and smart terms. He compares options across lenders, explains PMI and down payment choices, and makes sure the loan fits your long term goals. With clear communication and integrity, Jon makes the process smooth from start to close.

Conventional mortgage questions to review as a household

Compare the cash, insurance and repayment choices that fit the actual property. Conventional financing does not mean one universal set of terms.

Start with eligible programs for the property’s intended use, loan amount and documented finances. Conforming loans meet agency limits and rules; jumbo loans are generally conventional but nonconforming. The correct category helps make written quotes comparable.

It can preserve cash, while generally increasing borrowing and adding mortgage insurance. Eligible programs may permit as little as 3% down. Compare the complete monthly cost with the savings left afterward, rather than treating the minimum or maximum down payment as automatically preferable.

Income stability, recurring debts, assets, occupancy and the underwriting program all affect eligibility. Some affordable programs also have income limits. Ask for the criteria applying to the full application; one advertised score does not establish approval.

Ask for the servicer’s applicable cancellation process and relevant balance schedule. Many eligible borrower-paid PMI loans permit a request at 80% of original value with conditions and automatic termination at the scheduled 78% point when current. Increased-value cancellation follows separate requirements.

A change in county, unit count, condo project or intended use can affect eligibility and pricing. Current conforming limits apply to the loan balance. Tell the team about a new property promptly instead of assuming a quote for one home works unchanged for another.

Use matching purchase and down-payment assumptions, including all upfront fees and mortgage insurance costs. Review how long the insurance lasts and the expected balance over your ownership period. The lower interest rate alone does not identify the less costly arrangement.